IMF Global Market Risks Signal Dangerous Wave of Economic Volatility
The friction between sky-high technology valuations and the cold reality of rising debt costs has reached a critical flashpoint in the final quarter of 2026. As global capital flows navigate increasingly turbulent waters, the guardrails of the post-pandemic recovery are showing visible signs of strain. Recent reports focusing on IMF global market risks point toward a dangerous convergence of slowing technology sectors and rising borrowing costs worldwide. As international financial markets face mounting pressure, new warnings highlight critical vulnerabilities that could reshape the economic landscape for years to come.
The dual threat of a cooling artificial intelligence sector and rapidly climbing bond yields represents a synchronized risk that could trigger widespread equity selloffs and tighten global financial conditions.
How the AI Sector Slowdown Threatens International Markets
The International Monetary Fund (IMF) has recently identified an artificial intelligence slowdown as one of the most significant looming risks to global financial stability. For several years, the technology sector, particularly firms specializing in semiconductors and AI infrastructure, has served as the primary engine for equity market gains. However, the current assessment suggests that this momentum is cooling, leading to a profound reassessment of valuations across the tech landscape.
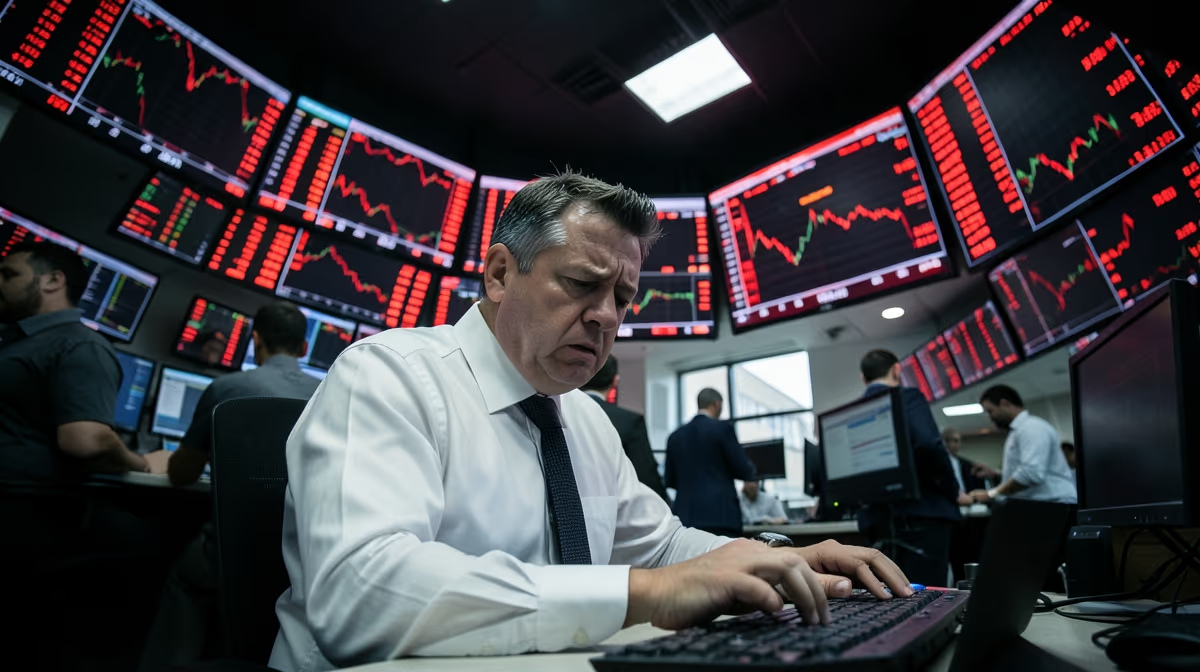
The broader implications of this slowdown are already manifesting in the chip sector. A deepening rout in semiconductor stocks has extended into Asian markets, marking a significant shift in investor sentiment. As the chip rout intensifies, regional trading hubs that are heavily dependent on tech exports are feeling the impact of these recalibrated growth expectations. Market participants are increasingly concerned that the massive financial boom driven by artificial intelligence might be reaching a period of exhaustion, leaving high-valuation tech firms vulnerable to sharp corrections.
The Mechanics of Technology Valuation Cooling
The IMF’s assessment suggests that the "AI enthusiasm" that previously drove concentrated market gains is now facing a period of skepticism. This is not merely a localized issue but a systemic one, as the interconnected nature of the global tech supply chain ensures that a slowdown in one region rapidly transmits to others. Analysts suggest that the root cause lies in unrealistic valuations that failed to account for persistent inflationary pressures and the eventual necessity of more cautious fiscal policies.
Spiking Bond Yields and the Trigger for Asian Stock Selloffs
While the technology sector faces its own internal cooling, a secondary and equally potent risk has emerged in the form of spiking bond yields. When sovereign bond yields rise, the cost of capital increases across the entire global economy. For governments and businesses, this means borrowing money becomes significantly more expensive, often leading to tighter financial conditions that can dampen economic growth and impact corporate earnings.
The current spike in yields is particularly concerning for the 2026 fiscal landscape. Persistent inflationary concerns and shifting central bank monetary policies have driven these yields higher, creating a "perfect storm" when combined with the tech slowdown. This environment has already triggered stock selloffs across major Asian exchanges, as investors pull back from riskier assets in favor of more stable, or defensive, positions.
- Spiking yields increase borrowing costs for both public and private sectors.
- Rising debt costs often lead to a reduction in corporate investment and consumer spending.
- The convergence of high yields and tech volatility is a classic trigger for broader market reevaluations.
A Shifting Landscape in Global Commodities
The impact of these macro-financial risks is not limited to stocks and bonds; it has also permeated the global commodity markets. Recent data indicates a complex and mixed performance across various asset classes, reflecting the uncertainty felt by global investors. Zinc prices, for instance, have seen a decline as the market shifts toward a modest surplus. This surplus is largely driven by an increase in refined supply, as reported by Kedia Advisory, indicating that even industrial metals are susceptible to shifting supply-demand dynamics amidst broader economic cooling.
In contrast, precious metals have shown diverging trends. While gold futures have seen a rise, silver futures have faced downward pressure in both domestic and global markets. These movements suggest a flight to quality for some investors seeking the traditional "safe haven" of gold, even as other industrial-linked metals like silver and zinc face headwinds.
| Commodity / Indicator | Recent Market Movement | Primary Driver |
|---|---|---|
| Zinc | Decline | Shift to modest surplus on higher refined supply |
| Gold Futures | Rise | Flight to quality amidst global market risks |
| Silver Futures | Fall | Mixed movement in domestic and global markets |
| Crude Oil | Trading at 107 | Saudi Aramco and global supply tracking |
| US CPI Data | Under Review | Key indicator for central bank policy |
Root Causes and the Historical Parallel
Market analysts point to a combination of factors that have led to the current instability. The root cause is identified as a dangerous mix of unrealistic valuations in the artificial intelligence sector and persistent inflationary pressures that continue to drive up sovereign bond yields. This situation mirrors historical market cycles, most notably the dot-com bubble correction of 2000. During that period, high-flying technology valuations deflated rapidly as broader macroeconomic tightening and rising interest rates took hold.
The correction in AI enthusiasm might accelerate a capital rotation toward defensive physical assets and raw materials, potentially altering trade balances for emerging economies.
This "hidden angle" of the current crisis suggests that as investors lose confidence in tech-driven growth, they may pivot toward physical assets. However, this rotation is complicated by the fact that the rising cost of capital makes it more difficult for emerging economies to finance the extraction and trade of these very raw materials.
The Political and Geopolitical Dimension
Governments worldwide are now facing a difficult balancing act. On one hand, there is immense pressure to continue providing subsidies for high-tech growth and domestic semiconductor manufacturing to ensure technological sovereignty. On the other hand, the reality of escalating borrowing costs necessitates fiscal restraint. This political tension is particularly acute in major economies where public budgets are already stretched by previous recovery efforts.
The geopolitical angle cannot be ignored. Global financial interconnectedness ensures that monetary tightening or tech-sector corrections in a major economy like the U.S. or China will rapidly transmit volatility to developing markets. As the IMF flags these synchronized risks, the potential for a "domino effect" in international trading becomes a central concern for global regulators and institutional investors.
Future Outlook: What to Expect Next
As we look toward the immediate future, the next 24 to 72 hours will be critical for determining the short-term trajectory of global markets. Investors are expected to maintain heavy pressure on tech stocks as they continue to process the IMF’s warnings. Financial analysts and market regulators will be closely monitoring shifting asset flows, particularly in regional trading hubs where bond yield volatility remains high.
Predicting the Paths Ahead
- Next 24 Hours: Global markets are likely to remain in a state of high alert, processing the IMF risk assessments. Tech stocks and regional hubs in Asia will remain under pressure as investors recalibrate their portfolios.
- Next 72 Hours: A focus on sentiment indicators and bond yield volatility will dominate the headlines. Regulators may begin to assess the need for stability measures if the selloff in the chip sector accelerates.
- Best-Case Scenario: Markets absorb the IMF warnings without triggering widespread panic. This would lead to an orderly adjustment in bond yields and a stable recalibration of tech valuations, allowing for a "soft landing."
- Worst-Case Scenario: A compounding effect occurs where spiking yields and a deeper AI slowdown accelerate broader equity selloffs. This could lead to a systemic liquidity crunch and a more severe global market correction.
Frequently Asked Questions
What are the primary risks the IMF is currently warning about?
The IMF has specifically cited a potential slowdown in the artificial intelligence sector and rapidly spiking bond yields as the two primary looming risks to the global economy in 2026.
How is the tech sector specifically affected?
The sector is experiencing a "cooling" of the AI-driven boom, which has already led to a chip rout and stock selloffs that have extended into major Asian markets.
What does a spike in bond yields mean for the average person?
Spiking yields lead to higher borrowing costs for businesses and governments. This can eventually lead to tighter financial conditions, making it more expensive to get loans for homes or businesses, and can impact retirement portfolios through market volatility.
Why are zinc prices falling if other assets are rising?
Zinc prices have declined because the global market has shifted into a modest surplus due to higher refined supply, showing that supply-demand fundamentals are still a key factor alongside broader economic trends.
Conclusion
The global financial landscape is currently navigating a period of significant transition and heightened risk. The International Monetary Fund’s identification of an AI slowdown and spiking bond yields as synchronized threats highlights the vulnerability of a market that has relied heavily on technology valuations and low borrowing costs. With stock selloffs deepening in Asia and commodity markets showing mixed signals, the importance of macro-financial stability has never been more apparent. Moving forward, the ability of global markets to recalibrate growth expectations without triggering a broader systemic crisis will depend largely on how investors and regulators react to shifting yield curves and the cooling of the high-tech sector. Central banks and global financial institutions remain the key players to watch as they attempt to balance inflation control with the need for continued economic stability.
Sources
- Global Market Today: Stock selloff extends to Asia as chip rout deepens — The Economic Times
- IMF cites AI slowdown, spiking yields as looming global market risks — Reuters
- Zinc Declines As Global Market Shifts To Modest Surplus On Higher Refined Supply By Kedia Advisory — Investing.com India
- Gold futures rise, silver futures fall in domestic, global markets — Business Standard
- global market updates us cpi data saudi aramco crude oil 107 — Zee Business
- Airport Updates: Latest News On The Global Market (W/C Oct. 12, 2026) — Aviation Week


